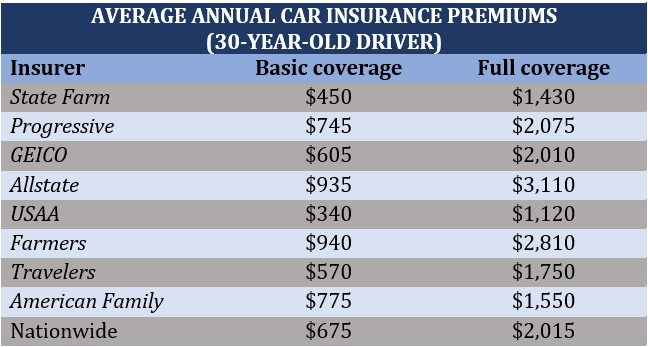
Auto insurance comparison rates refer to the process of evaluating premiums from multiple insurers to identify the most cost‑effective policy for a specific driver profile; for example, a 30‑year‑old driver in Ohio might see quotes ranging from $850 to $1,200 annually based on differing risk assessments.
Understanding these rates is crucial because insurance represents a significant recurring expense, and small percentage differences can translate into hundreds of dollars saved over a policy term; historically, the rise of digital aggregators in the early 2000s democratized access to pricing data, empowering consumers to make data‑driven decisions.
This article dissects the mechanics behind rate variations, highlights pitfalls to avoid, outlines discount opportunities, and equips readers with actionable steps for a thorough comparison.
1. Auto Insurance Comparison Rates
The term encapsulates both the numerical premium values and the underlying rating algorithms that insurers employ; these algorithms weigh factors such as driving history, vehicle type, and geographic risk. By juxtaposing multiple outputs, patterns emerge that reveal which carriers prioritize safety incentives versus profit margins.
Practically, a side‑by‑side spreadsheet can expose hidden fees, policy limits, and deductible structures, enabling a holistic assessment beyond headline numbers.
2. Pricing Dynamics
- Base Premium Calculation
Insurers start with a base rate derived from actuarial tables; a driver with a clean record may receive a base of $600, while a recent at‑fault accident adds a surcharge of $150, illustrating how risk layers affect the final quote.
- Geographic Multipliers
Urban centers often carry higher multipliers due to congestion and theft statistics; for instance, a driver in Detroit might pay 20% more than a counterpart in a rural county, underscoring the importance of location in rate differentials.
- Vehicle Profile Adjustments
High‑performance cars attract larger premiums because repair costs and accident severity are higher; a 2022 sports sedan could increase a quote by $200 compared with a standard sedan of similar age.
These dynamics interact, creating a mosaic of cost drivers that a thorough comparison must decode.
3. Coverage Variables
Beyond price, coverage limits, deductibles, and optional endorsements shape the value proposition; a lower premium may accompany a higher deductible, shifting out‑of‑pocket risk to the policyholder.
Evaluating liability limits, uninsured motorist protection, and comprehensive coverage ensures that cost savings do not compromise essential protection.
4. Common Mistakes
- Ignoring Policy Bundles
Many consumers overlook multi‑policy discounts; bundling auto and home insurance can shave 10%–15% off the auto rate, a saving invisible when quotes are examined in isolation.
- Overlooking Credit Scores
In states where credit-based pricing is permitted, a strong credit score can reduce premiums by up to 30%; failing to factor this variable yields an incomplete comparison.
- Failing to Update Information
Using outdated mileage or address data inflates quotes; a recent move from a low‑risk suburb to a higher‑risk city can add $100–$200 annually, emphasizing the need for current inputs.
Recognizing these errors prevents distorted conclusions and protects against hidden costs.
5. State Regulations
Regulatory frameworks differ markedly; some states mandate minimum liability limits, while others prohibit usage‑based pricing. Understanding local statutes helps interpret why two neighboring states may present divergent rate structures for identical driver profiles.
Compliance considerations also affect eligibility for certain discounts, such as safe‑driver programs that are state‑specific.
6. Discount Strategies
- Safe‑Driver Programs
Enrollment in telematics programs that monitor braking and acceleration can yield 5%–12% reductions, as demonstrated by a Midwest carrier offering $75 monthly savings for low‑risk behavior.
- Loyalty Rewards
Long‑term customers may receive multi‑year rate freezes; a provider in Texas offers a 3% loyalty discount after five consecutive policy renewals.
- Affiliation Discounts
Membership in professional organizations, alumni groups, or military service often unlocks exclusive rate cuts ranging from 4% to 10%.
Strategically stacking applicable discounts amplifies overall savings beyond the headline premium.
7. Choosing the Right Tool
Digital comparison platforms vary in data breadth, algorithm transparency, and partner networks; selecting a tool that aggregates quotes from at least ten reputable insurers ensures a robust sample set.
Additionally, platforms that provide side‑by‑side policy feature matrices enable deeper analysis of coverage nuances, facilitating an informed decision.
Frequently Asked Questions
Below are concise answers to common queries about auto insurance comparison rates.
Question 1: How do auto insurance comparison rates affect monthly premiums?
By revealing the spread of offers, comparison rates allow drivers to identify lower‑priced alternatives; selecting a policy even 10% cheaper can reduce a $100 monthly premium to $90, creating tangible long‑term savings.
Question 2: Which factors have the greatest impact on rate differences?
Driving history, geographic location, vehicle type, and credit score typically dominate premium calculations; each can shift rates by $50‑$300 depending on risk weighting.
Question 3: Are online comparison tools reliable for all states?
Most tools cover the majority of carriers, but in states with strict rate‑regulation or limited market participants, certain insurers may be omitted, requiring direct outreach for a complete picture.
Question 4: What common mistakes lead to inaccurate comparisons?
Neglecting to update personal data, ignoring bundled discounts, and overlooking state‑specific regulations often produce skewed results, inflating perceived costs.
Question 5: How can discounts be incorporated into rate analysis?
Identify applicable discounts—safe‑driver, loyalty, affiliation—and apply them to each quote; a systematic spreadsheet can track net premiums after discount application.
Question 6: When is it advisable to switch providers after a comparison?
Switching is prudent when a new policy offers a lower net premium, comparable or better coverage limits, and favorable customer‑service ratings, typically after a 12‑month review cycle.
Tips for Effective Comparison
Below are nine actionable tips to maximize the value of auto insurance comparison rates.
Tip 1: Verify Data Accuracy. Ensure mileage, address, and driving record details are current before generating quotes.
Tip 2: Include All Vehicles. Add each insured vehicle to the comparison to capture multi‑car discounts.
Tip 3: Assess Deductible Impact. Higher deductibles lower premiums but increase out‑of‑pocket risk; balance accordingly.
Tip 4: Factor in Discounts. List every eligible discount—safe‑driver, bundling, affiliation—to compute net costs.
Tip 5: Review Coverage Limits. Confirm that liability and comprehensive limits meet personal risk tolerance.
Tip 6: Compare Customer Ratings. Include insurer claim‑handling scores to weigh service quality alongside price.
Tip 7: Check State‑Specific Rules. Verify that quoted policies comply with local minimum coverage requirements.
Tip 8: Re‑evaluate Annually. Market conditions shift; a yearly review captures new discounts or rate changes.
Tip 9: Use Multiple Tools. Cross‑check results from at least two comparison platforms to avoid platform bias.
Conclusion
The examined aspects—pricing dynamics, coverage variables, common pitfalls, regulatory influences, discount strategies, and tool selection—collectively empower informed decision‑making when navigating auto insurance comparison rates.
Armed with these insights, drivers can consistently secure optimal protection at competitive prices, ensuring financial resilience on the road.

