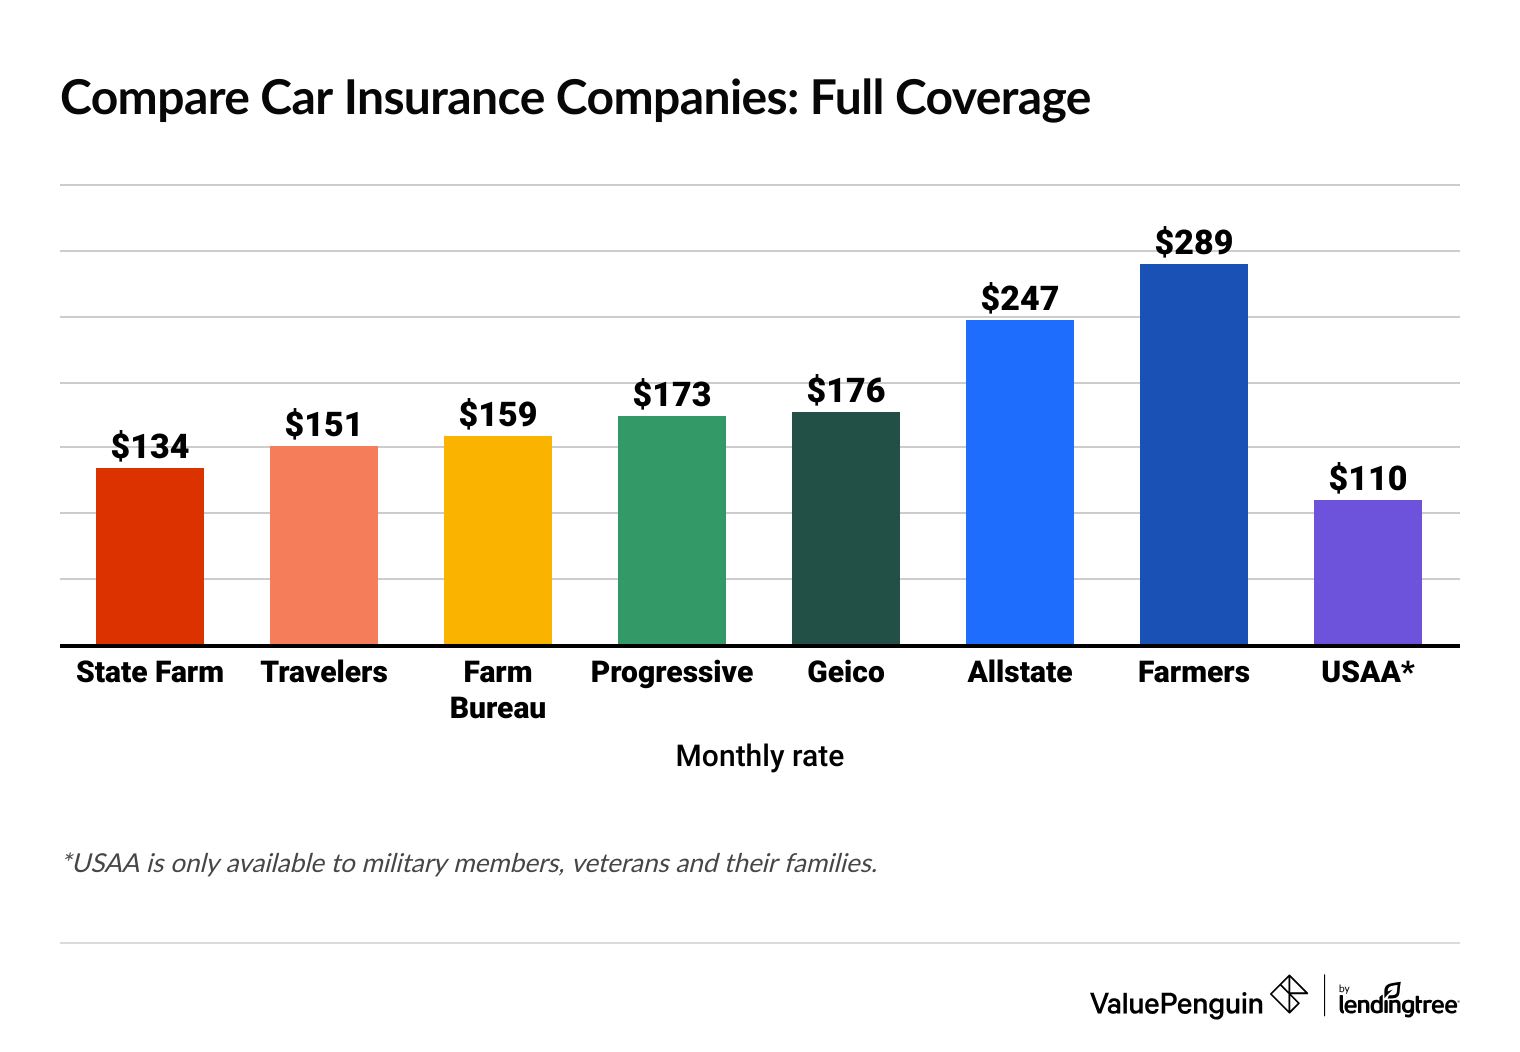
The **auto insurance quote rate** represents the estimated cost a driver pays for coverage before policy finalization, calculated by insurers using algorithms that weigh risk factors like driving history, vehicle type, and location. For example, a 30-year-old in Chicago with a clean record and a Toyota Camry might receive a quote rate of $1,200 annually, while a 25-year-old in Miami with a speeding ticket and a sports car could see $2,500—both reflecting statistical risk profiles. This rate serves as a benchmark for negotiation, where discounts, bundling, or higher deductibles can adjust the final premium.
Auto insurance quote rates hold significant weight in financial planning, influencing decisions on vehicle purchases, coverage levels, and even where to live. Historically, insurers relied on broad demographic data, but modern underwriting leverages real-time data like telematics (e.g., Progressive’s Snapshot) to refine rates dynamically. Lowering a quote rate by even 10% can free up funds for maintenance or emergencies, while overpaying may indicate missed discounts or misclassified risk. Understanding these rates empowers drivers to challenge unfair pricing or optimize their policies.
This guide breaks down the mechanics behind auto insurance quote rates, from the algorithms that generate them to the hidden levers that can reduce costs. It covers how insurers calculate risk, the role of credit scores, and why location matters more than many assume. Practical sections address common misconceptions, negotiation tactics, and tools to compare quotes accurately.
1. How Insurers Calculate Quote Rates
Auto insurance quote rates are derived from actuarial models that predict claim likelihood. Core inputs include driving record (e.g., accidents or tickets), vehicle make/model (e.g., a Tesla Model 3 costs less to insure than a Lamborghini Huracán due to repair costs and theft risk), and demographic factors like age and gender. Location plays a critical role: urban areas with higher accident rates or theft incidents (e.g., Detroit or Los Angeles) yield higher quote rates than rural regions. For instance, a driver in Boston might pay 30% more than one in Des Moines for identical coverage.
Insurers also factor in coverage limits and deductibles. A policy with $50,000 bodily injury liability and a $1,000 deductible will have a lower quote rate than one with $100,000 limits and a $500 deductible, as the insurer assumes less financial risk. State regulations further shape rates: no-fault states (e.g., Michigan) often have higher quote rates due to mandatory personal injury protection (PIP) coverage. Understanding these variables helps drivers identify where to trim costs without sacrificing protection.
2. The Role of Credit Scores in Quote Rates
Credit-based insurance scores—separate from traditional credit scores—directly impact auto insurance quote rates in most states. Studies show drivers with poor credit can pay up to 70% more than those with excellent credit, as insurers correlate financial responsibility with claim risk. For example, a driver with a 750 credit score might receive a quote rate of $900, while one with a 580 score could face $1,500 for the same coverage. This disparity stems from statistical links between credit history and behaviors like policy lapses or fraud.
**Key credit-related factors influencing quote rates:**
- Payment history. Late payments on loans or credit cards signal higher risk of missed premium payments. A driver with two late payments in the past year might see their quote rate increase by 20–30%. *Example:* A policyholder in Texas with a 680 credit score and one late utility bill could pay $1,300 annually, while a peer with a 720 score and no late payments might pay $1,050.
- Credit utilization. Maxing out credit cards suggests financial instability, prompting insurers to adjust quote rates upward. Utilization above 30% can add 10–15% to the rate. *Example:* A California driver with $5,000 in credit card debt on a $10,000 limit (50% utilization) might face a $1,400 quote rate, compared to $1,100 for someone with $1,500 debt on the same limit.
- Credit history length. Shorter credit histories (e.g., recent graduates) lead to higher quote rates due to limited data. A 22-year-old with two years of credit might pay 25% more than a 40-year-old with a decade-long history. *Example:* Two identical policies in Florida—one for a driver with five years of credit, the other with none—could differ by $300 annually.
Improving credit scores over time can lower quote rates significantly. For instance, paying down debt or becoming an authorized user on a family member’s card can boost scores within months, leading to savings of hundreds per year.
3. Location’s Hidden Impact on Quote Rates
Geographic data is one of the most influential yet overlooked factors in auto insurance quote rates. Insurers analyze ZIP codes for accident frequency, crime rates, and even weather patterns. Urban areas like New Orleans or Oklahoma City face higher quote rates due to storm damage claims, while suburban regions like Madison, Wisconsin, offer lower rates thanks to lower accident statistics. Even within a city, neighborhoods vary: a driver in Chicago’s Lincoln Park might pay 20% less than one in Englewood for the same coverage.
**Location-based variables affecting quote rates:**
- Accident frequency. High-traffic areas with poor infrastructure (e.g., parts of Atlanta or Houston) inflate rates due to collision claims. A driver in Atlanta’s Buckhead might pay $1,100, while one in a quieter suburb could pay $850. *Implication:* Relocating or adjusting commute routes can reduce exposure.
- Theft risk. Cities with high vehicle theft rates (e.g., Oakland or St. Louis) increase comprehensive coverage costs. A Honda Civic in Oakland could add $200–$400 to the quote rate compared to the same car in a low-theft area. *Example:* Theft claims in Oakland cost insurers $500 million annually, raising premiums citywide.
- Weather-related claims. Regions prone to hail, floods, or hurricanes (e.g., Dallas or Miami) see higher comprehensive coverage rates. A driver in Dallas might pay an extra $150 for hail damage coverage versus $50 in Phoenix. *Example:* Texas hailstorms cost insurers $2.5 billion in 2022 alone.
Insurers also use proxy data like proximity to emergency services. Drivers near fire stations or hospitals may receive slightly lower quote rates, as response times reduce claim severity. Tools like the Insurance Institute for Highway Safety’s (IIHS) state-by-state cost analysis can reveal these disparities.
4. Vehicle-Specific Factors in Quote Rates
The type of vehicle insured is the second-largest determinant of auto insurance quote rates after location. Insurers categorize cars by repair cost, safety ratings, theft vulnerability, and engine size. A 2023 study by the Insurance Information Institute (III) found that luxury cars like the BMW M3 cost 40% more to insure than mid-size sedans like the Honda Accord, primarily due to higher collision repair costs and parts prices. Even within the same brand, models vary: a Toyota RAV4’s quote rate may be 15% lower than a Lexus RX, as the latter’s premium parts drive up claims.
Anti-theft technology and safety features also lower quote rates. Cars equipped with factory-installed systems like OnStar or advanced driver-assistance (ADA) tools (e.g., Tesla’s Autopilot) can reduce rates by 5–10%. For example, a 2022 Subaru Outback with EyeSight might receive a quote rate $100 lower than an identical model without the system. Insurers reward these features because they correlate with fewer accidents and lower claim payouts. Additionally, vehicles with high safety ratings from the IIHS or NHTSA often qualify for discounts, as they reduce injury severity in crashes.
5. Common Mistakes That Inflate Quote Rates
Many drivers unknowingly inflate their auto insurance quote rates through avoidable behaviors or oversights. These missteps can add hundreds or even thousands to annual costs without providing proportional protection. For instance, failing to disclose a minor accident or ticket can void coverage and trigger rate hikes retroactively. Similarly, underestimating coverage needs—such as opting for state-minimum liability limits—can lead to higher out-of-pocket expenses in a claim, indirectly increasing the effective

